Budgeting on irregular income.
Use a buffer to steady your spending.
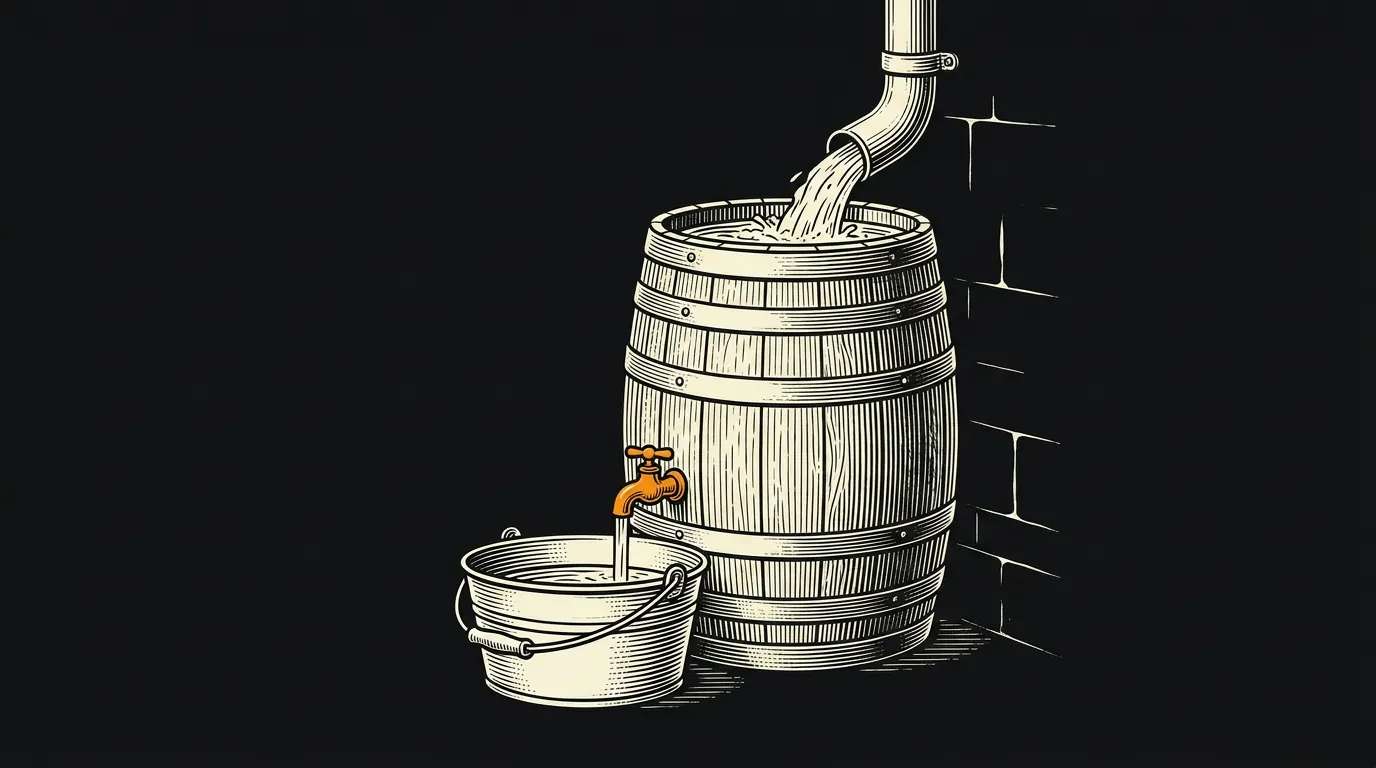
The standard monthly budget assumes the same paycheck every month. Freelancers, servers, commissioned salespeople, and seasonal workers need a different system. The fix is a buffer account that absorbs income variability so your spending account always sees the same amount.
1099 tax handling and SEP/Solo 401k references are US-specific. The two-account buffer system applies anywhere.
This page covers how to build and run the buffer that smooths a variable paycheck. For the full freelancer money plan, see Irregular Income (Any Age).
The fix is a buffer account that absorbs income variability so your spending account always sees the same fixed amount. Your income fluctuates. Your financial life doesn't have to. Set the monthly transfer at the amount that works in your worst typical month, not your average month. Build the buffer first, then start the system.
On this page
Why standard budgets fail on irregular income
A monthly budget built for a $5,000 fixed paycheck fails for someone earning $2,000 one month and $8,000 the next. Three reasons:
- It creates false expectations. Budgeting $5,000 when income is $2,000 means the math is wrong six months per year.
- It forces binary decisions. Good month: feel rich, spend more. Bad month: panic, cut everything. The reaction to volatility is the problem, not the volatility itself.
- It doesn't account for quarterly or annual income spikes (bonuses, tax season, holiday tips).
The two-account buffer system
Setting the transfer amount
Start with your minimum monthly expenses: rent or mortgage, utilities, groceries, insurance, loan minimums. Add a reasonable discretionary amount. This is your monthly "salary" to yourself. Set it at the amount that works in your worst typical month, not your average month.
- Good month: more money sits in the income account. You transfer the same fixed amount. The excess accumulates.
- Bad month: less came in. You transfer the same fixed amount. The buffer absorbs the shortfall. Your financial life is unchanged.
Buffer math
Size the buffer to cover 2 to 3 months of fixed expenses. Build it before starting the system. A depleted buffer is the signal that your fixed transfer is too high. Replenish before increasing the transfer.
The Two-Account Buffer System
Methodology: fixed transfer set at the amount that survives your worst typical month. Buffer absorbs short months; excess refills it during good months.
The tax reserve (1099 income)
If you receive 1099 income, set aside 25 to 30% of every payment into a dedicated savings account the day it arrives. This is not your money. It belongs to the IRS and your state. Pay quarterly estimated taxes verify×DON'T TRUST, VERIFYClaim: Self-employed and 1099 workers must generally pay quarterly estimated taxes to avoid underpayment penalties.Verify at: IRS Topic 306: Estimated tax ↗ Source 1 in the list belowQuarterly deadlines: April 15, June 15, September 15, January 15. Safe-harbor: pay 90% of current year or 100% of prior year (110% if AGI > $150K)..
Do not spend the tax reserve. Not temporarily. Not just this once. Commingling tax money with spending is how freelancers end up with IRS debt.
Annual income events
Seasonal workers, commissioned salespeople, and some freelancers have predictable annual income patterns: a big Q4, a slow January, a summer surge.
Map your income history
Look at 24 months of income. Identify your lowest 3 months and your highest 3 months. Your fixed monthly transfer should be sustainable in the worst 3-month stretch without depleting the buffer.
Bonus discipline
When a large payment arrives (big contract, bonus, tax return), do not treat it as discretionary income. Allocate first:
- Top up the buffer to target.
- Fund the emergency fund to target.
- Max any tax-advantaged accounts not yet maxed.
- Pay down high-interest debt.
Whatever remains: that is the discretionary portion.
Retirement accounts on irregular income
The standard advice (contribute a fixed percentage of each paycheck) works automatically on W-2 income. On 1099 income, you must choose to contribute from each payment.
The system: every time income hits the income account, transfer 15 to 20% to a SEP IRAIndividual Retirement Account (IRA)A retirement account with tax advantages and eligibility rules. Traditional IRA contributions may be deductible; taxable withdrawals generally enter income. Roth contributions use after-tax money, and qualified Roth withdrawals are tax-free.Full definition or Solo 401k at the same time you transfer to the tax reserve. Treat it as automatic even if manual. The alternative (review quarterly and make a lump-sum contribution) requires discipline most people don't maintain. The automatic per-payment approach is more reliable.
What this changes for tomorrow
- Open a separate savings or checking account at the same bank to be the income account. Direct all income there.
- Calculate your worst 3-month stretch from the past two years. That number sets your fixed monthly transfer.
- Open a tax reserve account if you receive 1099 income. Set aside 25 to 30% of every payment, automatically, the day it arrives.
Where to go from here
Sources
Verify badges in the text link to these sources. Figures, rates and rules change: check each source’s date before acting on it.
- Internal Revenue Service, IRS Topic 306: Estimated tax ↩
Last updated . Not financial or tax advice. Quarterly estimated tax rules vary by income level; consult a tax professional. Disclosures · How pages are reviewed