How to retire on Bitcoin:
withdrawal strategy when your primary asset can drop 77%.
The 4% rule was built for stock-and-bond portfolios. Bitcoin has different volatility, different tax treatment, and a different risk profile in early-drawdown years. A Bitcoin retirement plan that relies on the same math that works for 60/40 breaks the first time Bitcoin drops 80% in your retirement year. Here is a framework to stress-test, not a guarantee.
This page covers US-specific accounts and tax law. Outside the US? The priority order is the same, the account names differ (ISAIndividual Savings Account (ISA)A UK tax-advantaged account where contributions are post-tax but all growth and withdrawals are tax-free.Full definition in the UK, TFSATax-Free Savings Account (TFSA)A Canadian tax-advantaged account where contributions are post-tax but all growth and withdrawals are tax-free.Full definition/RRSPRegistered Retirement Savings Plan (RRSP)A Canadian tax-deferred retirement account; contributions reduce taxable income and growth is tax-deferred until withdrawal.Full definition in Canada, Super in Australia, etc.).
This page covers the drawdown-phase policy: buckets, cash-buffer sizing and withdrawal order. For whether Bitcoin retirement is feasible at all, see Retire on Bitcoin; for sale timing and tax mechanics, see Exit Strategy; for the SCHD income floor in depth, see Dividend Income Floor.
A cash reserve and diversified income assets can reduce the need to sell Bitcoin at an inconvenient time, but they do not guarantee a safe retirement. Set a written spending, allocation and rebalancing policy. Review the plan when the reserve falls, income changes or risk capacity shrinks; selling during a drawdown can be appropriate. Bitcoin recovery is not guaranteed.[1]
On this page
Why the 4% rule doesn't translate directly
The Trinity Study used rolling historical periods of US stock and bond data. Worst historical 4-year drawdown for a 60/40 portfolio: roughly 40-45% verify×DON'T TRUST, VERIFYClaim: 60/40 portfolio worst 4-year drawdown ~40-45%.Verify at: Kitces research ↗ Source 1 in the list below1929-1932 and 2007-2009 windows are the typical worst cases. Varies by specific asset mix..
Bitcoin's worst peak-to-trough drawdown after 2011: roughly 85% during the 2017-2018 cycle verify×DON'T TRUST, VERIFYClaim: Bitcoin's worst peak-to-trough drawdown after 2011 was ~85% in 2017-2018.Verify at: Bitcoin Price History ↗~$19,800 peak December 2017 to ~$3,200 trough December 2018..
If you retire in year one of an 85% Bitcoin drawdown and you're withdrawing at a 4% rate from a Bitcoin-heavy portfolio, the math breaks. Your portfolio is worth 15 cents on the dollar AND you're pulling from it. The sequence-of-returns problem is amplified, not eliminated.
The three-bucket strategy
The purpose of separate buckets is cash-flow planning, not an instruction to hold one asset at any cost. A finite cash reserve may buy time. It can also run out before markets recover. The plan needs a depletion trigger, an adjustable spending budget and a diversified source of future withdrawals.
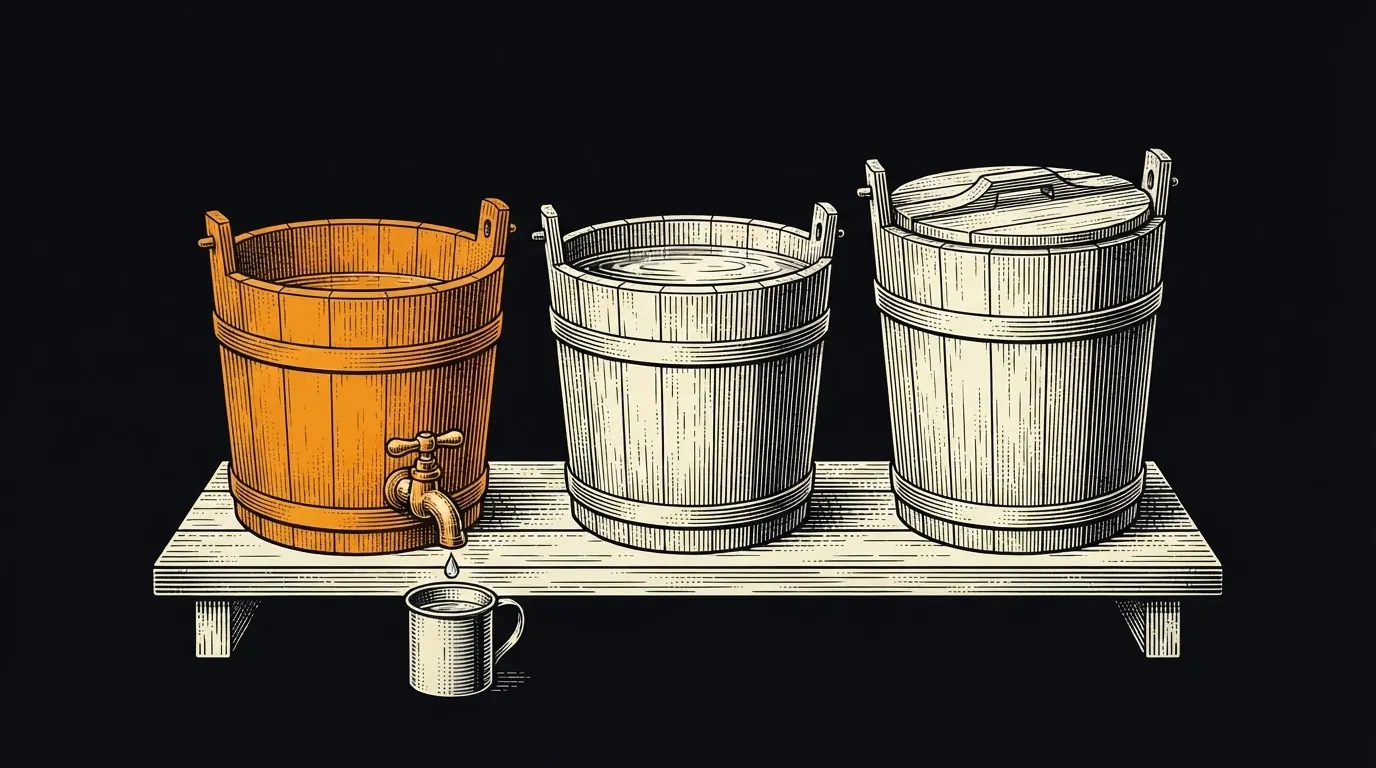
Cash buffer: 2-3 years of living expenses
Hold near-term spending money in accessible accounts or short-duration assets selected for the required liquidity and protection. Spending reduces this balance. Choose a review threshold and refill rule in advance; do not assume a Bitcoin bull market will arrive before the reserve is depleted.
Income floor: SCHD + bonds + I-Bonds
This bucket may hold a diversified mix of bonds and income-producing investments. Interest and dividends depend on the holdings; dividends can be cut and bond values can fall. A dividend equity fund is not a guaranteed income floor or a substitute for deposit insurance.
Bitcoin: long-term store of value
Bitcoin is the speculative part of the plan. Choose exposure so a severe loss would not make essential spending depend on a price recovery. Use written allocation and withdrawal rules instead of a promise to sell only above a past peak or personal cost basis.
A refill policy can use scheduled reviews, current spending needs and allocation drift. Consider gains, losses, tax consequences and the rest of the portfolio together. Cost basis matters for tax records, but it is not a guarantee of a future recovery or the sole reason to keep an unsuitable position.
How much cash buffer do you need?
An illustrative reserve target is monthly essential spending multiplied by a chosen number of months. The horizon should reflect reliable income, liquidity, risk capacity and spending flexibility; no fixed two- or three-year reserve guarantees survival. Stress-test a longer drawdown and a permanent Bitcoin loss. Define what spending, allocation or timing would change before depletion, and review those choices with a qualified planner.
Bitcoin has historically recovered to new highs within about 3.2 years of every major peak before 2025. 2-3 years of buffer means you can ride out most drawdowns without selling. "Historically" is the load-bearing word. It is not guaranteed.
The SCHD income floor
$500,000 in SCHD at 3.5% yield: $17,500/year = $1,458/month.
$1,000,000 in SCHD: $35,000/year = $2,917/month.
Dividends can grow, stay flat or be cut. A yield assumption is not a promised payment. Compare expected after-tax income with essential spending, and test a simultaneous decline in dividends and asset prices. Insurance or annuity benefits, if used, depend on their specific contracts and provider risk.
If your basic living expenses are covered by dividends, Bitcoin becomes pure offense: sell it to upgrade lifestyle, fund large purchases, or leave as inheritance. You never sell defensively. That's the core exit strategy this site recommends. Full treatment: Dividend Income Strategy.
Tax-efficient withdrawal order
- Cash (Bucket 1) first. Zero tax impact.
- Taxable brokerage. Long-term capital gainscapital gainsThe profit from selling an asset for more than you paid for it. Taxed differently depending on how long you held the asset. rates.
- Traditional 401(k)/IRAIndividual Retirement Account (IRA)A retirement account with tax advantages and eligibility rules. Traditional IRA contributions may be deductible; taxable withdrawals generally enter income. Roth contributions use after-tax money, and qualified Roth withdrawals are tax-free.Full definition. Ordinary income rates. Roth conversionRoth conversionMoving eligible retirement money into a Roth account. Pre-tax amounts and earnings generally create taxable income; nondeductible basis is treated under the applicable aggregation rules. Conversions can affect tax brackets and income-based costs, and separate withdrawal rules apply.Full definition ladder (see here) can reduce this.
- Bitcoin. Taxable event, so time it carefully. See below.
- Roth IRA last. Tax-free, no RMDsRequired Minimum Distribution (RMD)The minimum the IRS requires you to withdraw each year from traditional IRAs, 401(k)s, and similar accounts, generally starting at 73, or 75 if born in 1960 or later. It equals the prior December 31 balance divided by an IRS life expectancy factor. Roth IRAs and Roth 401(k)s have no RMDs during the owner's lifetime., best inheritance vehicle.
Bitcoin-specific tax timing: long-term gains may use the 0% federal capital-gain band, but ordinary taxable income uses that band first and gains themselves count toward its ceiling. For 2026 the top of the 0% band is $49,450 of taxable income for a single filer and $98,900 for married filing jointly. Only the portion of qualifying gains that fits in the remaining band receives that rate; state taxes and other income-based interactions can still apply. Compare a planned sale with your full tax return and benefit situation rather than assuming a low-income year makes the entire sale tax-free.[2] See withdrawal sequencing for the planning framework.
What if Bitcoin never recovers?
A prolonged drawdown and a total loss are different scenarios; test both. No new high is required for a portfolio to need rebalancing. If the reserve is running down or income is insufficient, reassess spending, asset sales, retirement timing and available benefits rather than waiting indefinitely for Bitcoin to recover.
- Dividends may be reduced or suspended; a dividend fund does not provide a guaranteed floor.
- The cash reserve is finite and falls as it is spent; the contingency plan must address depletion.
- The Roth account contains investments whose values can rise or fall; the account label does not guarantee growth.
- In a total-loss scenario, the Bitcoin holding contributes nothing to future spending. Other assets must be stress-tested rather than assumed to be unaffected.
That's the actual risk. Size your Bitcoin allocation so that if this happens, your other assets still cover your basic needs. This is position sizing. See Bitcoin Allocation and the honest bear case.
Where to go from here
Sources
Bracketed numbers and verify badges in the text link to these sources. Figures, rates and rules change: check each source’s date before acting on it.
- Kitces research ↩
- 26 CFR 601.602: Tax forms and instructions.. Checked for this targeted correction; 2026 tax-year scope. ↩
- Some things you need to know - Bitcoin. Bitcoin.org identifies Bitcoin as a high-risk asset and explains custody and loss risks.
- Schwab SCHD fact sheet
- IRS capital gains topic
Last updated . Not financial advice. US-specific tax treatment; international readers should consult local tax law. Disclosures · How pages are reviewed